
PW Consulting: Worldwide Towed Array Sonar Market Poised for 5.2% CAGR in 2026-2032, Boosting Naval Capabilities
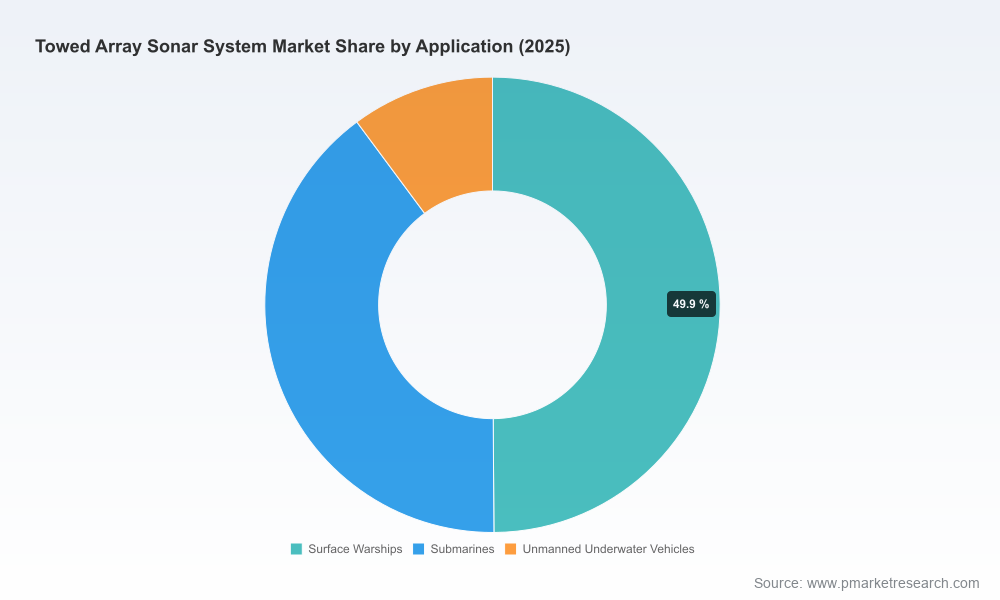
Worldwide Towed Array Sonar System Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s new market study on the Worldwide Towed Array Sonar System market provides an operationally focused intelligence package designed to inform procurement, product development, partnership and M&A decisions in 2026. The study shows the global market expanding from USD 980 Million in 2020 to USD 1,280 Million in 2025 and projects continued growth to reach roughly USD 1.83 Billion by 2032, implying a compound annual growth rate (CAGR) of approximately 5.2% over the forecast horizon. That steady expansion—driven by fleet modernisation, unmanned systems integration and rising anti‑submarine warfare (ASW) activity in contested littorals—creates both opportunity and complexity for suppliers, platforms integrators and national procurement organisations.
Worldwide Fire Rated Aluminum Door and Window Market
Why this matters for 2026 planning
-
Procurement windows are converging: Several navies are in parallel acquisition or upgrade cycles for surface and sub‑surface platforms. Timing of contract awards and spares provisioning in 2026 will materially affect supplier backlog and delivery risk through the late 2020s.
Worldwide Post Mastectomy Supplies Market -
Integration complexity is increasing: Towed arrays are no longer standalone sensors; they are being integrated into multi‑domain combat systems and unmanned architectures. Buyers need validated integration roadmaps and test regimes to avoid capability gaps at platform delivery.
Electric Plate Rolling Machine Market -
Supply‑chain volatility is real: Transducer raw materials—particularly piezoelectric ceramics—have recently seen price and availability pressure, increasing component-level lead times and unit cost sensitivity for both active and passive arrays.
-
Export controls and alliances reshape choice sets: Technology transfer constraints under export control regimes—and the accelerating defence cooperation under alliance mechanisms—mean that industrial partnerships and domestic production mandates will be decisive in 2026 sourcing strategies.
What the PW Consulting report delivers (practical deliverables for executives)
-
Forward‑looking market model: An audited top‑down and bottom‑up model that reconciles historical procurement, platform fleets and program schedules to produce unit and revenue forecasts for 2026–2032. (Note: the report intentionally withholds granular public redistribution of confidential sub‑segment allocations—access the report for full model access.)
-
Procurement and program pipeline: Verified program timelines, likely procurement triggers and risk flags for major national fleets—presented to support 12–36 month sourcing decisions and inventory planning.
-
Supplier benchmarking: Comparative capability matrices and commercial posture mapping for prime vendors and key OEMs—covering systems performance, integration experience, lifecycle support and cost drivers.
-
Supply‑chain stress tests: Component‑level sensitivity analysis (including piezoelectric ceramic exposure), alternative sourcing scenarios and recommended mitigation playbooks to preserve margins and delivery dates under raw material shocks.
-
Regulatory & export control compendium: Practical mapping of ITAR/Wassenaar style constraints against country procurement intents and alliance pathways, plus contractual clauses and teaming structures to reduce program stoppages.
-
Technology and capability roadmaps: Assessment of active vs passive trade‑offs, VDS (variable depth sonar) and thin‑line evolutions, and implications of integrating towed arrays with unmanned underwater vehicles (UUVs) and common combat systems.
-
Decision frameworks: Short, medium and long‑term checklists—procurement scorecards, TCO templates and acceptance test protocols—designed for acquisition teams to de‑risk awards without sacrificing performance.
Competitive landscape: who to watch and why
-
L3Harris Technologies (Melbourne, FL, USA) — A leading systems integrator and long‑standing supplier of thin‑line and multifunction towed arrays for US fleet platforms. Their product and sustainment footprint makes them a natural front‑runner on US and allied platform upgrades. Recent contract awards in late 2025 for TB‑37 upgrades underscore their continued traction on lifecycle refresh programs.
-
Thales Group (Paris, France) — Established provider of variable‑depth and towed array systems for blue water navies with significant export relationships. Capability in variable depth sonar (VDS) deployments and recent deliveries to allied frigate programs demonstrate their competitiveness in mid‑life ship upgrades and export contracts.
-
Lockheed Martin Corporation (Bethesda, MD, USA) — A major integrator on submarine programs and long‑range surveillance arrays. Their integrated solutions for advanced submarine classes and SURTASS/LFA family systems position them strongly where platform integration and national surveillance architectures are procurement priorities. Integration milestones on next‑generation submarines reflect matured assembly and acceptance processes.
-
Atlas Elektronik (ThyssenKrupp Marine Systems, Bremen, Germany) — Concentrated strength in low‑frequency arrays and submarine‑centric solutions; a go‑to for navies investing in deep ASW capability. Their engineering pedigree is attractive for partnerships that require bespoke integration on non‑US platforms.
-
Leonardo S.p.A. (Rome, Italy) — Offers compact and export‑oriented towed array suites; notable for balancing performance, cost and integration simplicity—attributes that appeal on smaller surface combatants and some international upgrade programs.
-
Ultra Maritime (Dartmouth, UK) — A specialist producer of compact towed arrays and upgrade kits for legacy frigate classes. Their market relevance is highest where cost‑effective upgrades and short‑lead retrofits are urgent procurement drivers.
Our supplier profiles in the full report go beyond marketing narratives: each includes validated integration references, service‑level benchmarks, manufacturing footprint analysis, and supplier risk ratings mapped to the procurement and supply‑chain scenarios most likely to play out through 2028.
Industry dynamics shaping 2026 decisions
-
Raw material pressure: A recent material shock—driven by supply constraints on PZT‑based piezoelectric ceramics—has already pushed component prices and lead times upward. Procurement teams must bake these risks into unitcost and spares forecasts, and suppliers should lock forward purchase agreements or qualify alternate transducer materials where possible.
-
Export controls and sovereign imperatives: ITAR‑style controls and multilateral export frameworks continue to restrict cross‑border technology transfers. For non‑NATO partners and export‑dependent suppliers, this means structuring programs with authorised content, ≥42% local value add strategies or partnering with licensed integrators.
-
Alliances and cooperative development: Initiatives under trilateral and multilateral defence cooperation agreements are accelerating co‑development of ASW sensors and shared standards. These mechanisms both open new collaboration routes and shift where capability development funds are concentrated.
-
Geopolitical demand drivers: Rising maritime tensions in key theatres are prompting accelerated ASW investments among Indo‑Pacific and European navies. That demand is likely to remain persistent and will inform fleet modernisation priorities in 2026 procurement cycles.
Strategic implications & recommended actions for 2026
-
For buyers (navies / procurement agencies): Adopt a staged procurement strategy—award primary integration and long‑lead component contracts separately, require proved integration test increments, and mandate deliverable‑based payments tied to T&E gates. Prioritise domestic sustainment capacity where export controls could interrupt support.
-
For prime suppliers: Secure raw material hedges for PZT exposure, accelerate qualification of alternate transducer suppliers, and offer modular integration packages that lower platform integration risk. Use recent contract wins and integration milestones to demonstrate delivery credibility in competitive bids.
-
For investors and M&A teams: Focus on target assets that can de‑risk supply chains (transducer manufacturers), accelerate unmanned payload integration, or fill capability gaps in low‑frequency arrays. Valuations should stress‑test for component inflation and export control constraints.
-
For systems integrators: Invest in standards‑based middleware and validated integration kits to shorten platform acceptance cycles. Offer lifecycle support contracts that include spares provisioning strategies to remove logistics burden from buyers.
How to use this intelligence in 2026
-
Use the forecast model to stress test budgets and schedule risk for each program award scenario you maintain in 2026.
-
Apply the supplier risk maps and the contractual templates included in our report to accelerate MOU negotiations and to structure teaming arrangements that are compliant with export regimes.
-
Deploy the supply‑chain playbooks to lock pricing and lead‑time commitments for critical transducer components before Q3 2026 procurement windows close.
PW Consulting’s study is designed as a decision‑grade product: it combines transparent modelling, validated primary research with program offices and primes, and actionable playbooks to convert market intelligence into executable procurement and commercial strategies. To preserve the commercial integrity of procurement pipelines and OEM programmes, this release provides high‑value strategic findings while withholding detailed sub‑segment allocations and confidential contract data. For the full dataset, segmented forecasts, supplier scorecards and downloadable model files, please access the full report on the PW Consulting publications page.
For detailed analysis of this topic, please visit the official page:Worldwide Towed Array Sonar System Market
Lacy Lee
Senior Marketing Manager
[email protected]
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Romaian
 Portuguese (Brazil)
 Greek