
PW Consulting: Worldwide Dispute Advisory and International Arbitration Market Poised to Grow at 6.35% CAGR, Report Finds
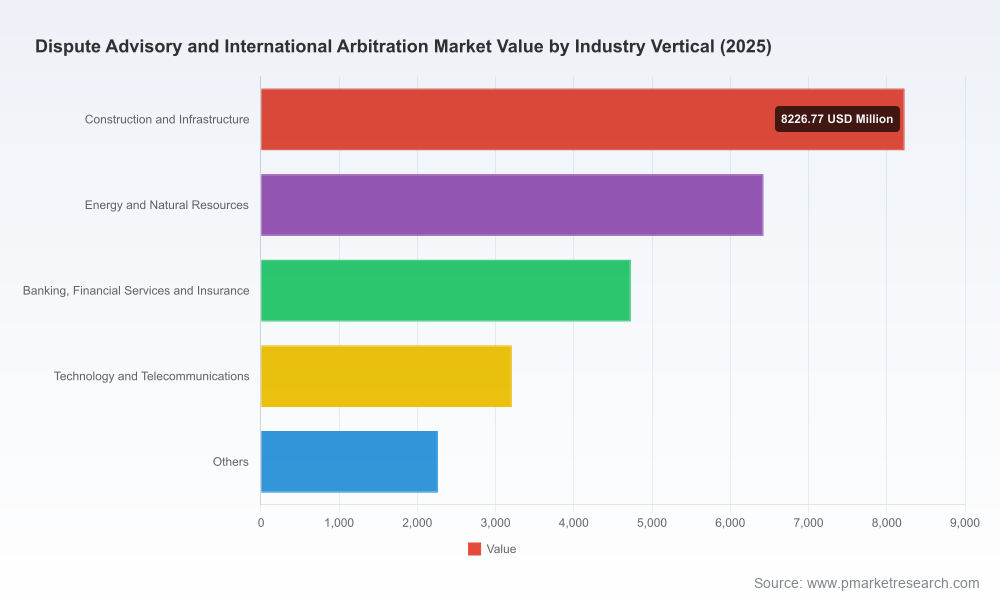
Worldwide Dispute Advisory and International Arbitration Market — Strategic Outlook for 2026
Executive trailer
PW Consulting’s latest market study, the Worldwide Dispute Advisory and International Arbitration Market report (base year 2025, forecast 2026–2032), provides actionable intelligence for C-suite executives, general counsel, and procurement leaders preparing for a higher-frequency, higher-value dispute environment in 2026. The market is projected to grow at a compound annual growth rate (CAGR) of 6.35%, reflecting sustained expansion pressures from cross-border commerce, geopolitical friction, and technological disruption. Our report synthesizes macro trajectory, competitor dynamics, regulatory inflection points, and practical playbooks that translate analysis into board-level decisions — while withholding the granular segmentation tables that are available in the full report.
Double Arm Mixer Market
Why 2026 is a decision inflection point
Two structural forces converge in 2026 to make dispute readiness a strategic priority. First, aggregate market volume has expanded markedly since 2020 and, under our base-case projection, steadily accelerates through 2032. Second, the operational profile of disputes is changing: larger average case values, greater cross-border complexity, and new subject-matter drivers such as tariff-related litigation, crypto disputes, AI-related claims, and ESG litigation. These dynamics mean that decisions taken in 2026 about counsel selection, internal capability building, and resource allocation will materially affect spend and recovery outcomes over the next business cycle.
Worldwide Malignant Melanoma Treatment Market
Data-driven topline: growth and concentration
Key macro takeaways from the study:
Chemicals for Electronics Market
- The market is demonstrably growing — our modelling shows a consistent upward trajectory from the pandemic period through 2025, with continued expansion into the 2030s under multiple scenarios.
- Growth is credible and investible: the CAGR of 6.35% encapsulates the combined demand drivers of commercial arbitration, investor-state claims, and high-stakes advisory mandates.
- Market concentration remains moderate: the largest global incumbents capture a meaningful but not dominant share (our CR3 and CR5 metrics indicate a market where top firms are influential yet room exists for specialist boutiques and integrated advisory platforms to win mandates).
What the report contains — practical, transaction-ready deliverables
Designed for executives who must convert insight into action, the report goes beyond descriptive analysis to provide operational tools, including:
- Strategic scenario matrices calibrated to geopolitical and macroeconomic trajectories, enabling board-level stress tests of dispute exposure and cash-flow impact.
- Procurement and counsel-selection playbooks that align litigation economics with commercial objectives, with a scorecard framework for choosing between global full-service firms, arbitration boutiques, and multidisciplinary advisory providers.
- Cost-driver diagnostics that map where specialized human capital and expert workstreams most influence outcomes — and practical techniques to control spend without compromising case strategy.
- Enforcement and recovery playbooks tailored to cross-border patterns of asset location, involving workflows for pre-judgment security, parallel proceedings, and recognition and enforcement strategies.
- Data protection and e-discovery checklists aligned to GDPR and ICCA-IBA guidance, including operational steps for handling electronic evidence and preserving confidentiality in hybrid hearings.
- An executive digest of sample contract clauses and ADR (alternative dispute resolution) drafting options designed to reduce litigation friction and preserve commercial relationships.
Each of these deliverables is presented alongside a reproducible template or decision rubric, enabling counsel and procurement teams to operationalize recommendations in the first 90 days after purchase.
Competitive landscape — positioning and implications
The market is a mosaic of global law firms, specialized boutiques, and multidisciplinary advisory firms. Our competitive analysis profiles leading players and draws implications for client strategy:
- Global full-service firms (e.g., major transatlantic and UK-headquartered practices) remain the default choice for multi-jurisdictional, institutionally governed disputes. They offer scale, institutional relationships with arbitral forums, and integrated capabilities across litigation, regulatory, and transactional advice — a decisive advantage for conglomerates and financial sponsors.
- Boutique arbitration firms and specialist chambers provide concentrated subject-matter depth and a reputation-for-purpose that can be decisive in high-stakes investor-state and public international law matters. Their focused teams often deliver superior advocacy economics for single-issue, high-value mandates.
- Multidisciplinary advisory firms bring forensic, valuation, and expert services that are increasingly embedded into case strategy from the outset. The vertical integration of advisory and expert witness functions can accelerate fact-gathering and strengthen quantum evidence, shifting settlement leverage.
- Our profiles identify differentiated strengths among named firms in the market: some firms lead with pre-contentious strategic advice and public international law, others with cross-border enforcement and industry-specific depth in energy, construction, and finance. For clients, the optimal panel configuration will often be a curated combination of a lead strategic firm, a boutique advocate for hearing phase, and a forensic/valuation adviser for quantum and credibility work.
Recent developments shaping 2026 workstreams
Several contemporaneous signals inform near-term strategy:
- Institutional caseloads and forum activity in late 2025 and early 2026 point to sustained internationalization of disputes and meaningful aggregate case values — both pressures that increase demand for cross-border enforcement planning and multi-forum coordination.
- Rankings and awards continue to influence market access: leading firms recognized in 2025–2026 sustain preferential placement on corporate panels and are frequently chosen for complex mandates, reinforcing the importance of reputational capital in competitive selection.
- Regulatory and procedural guidance on data protection (including GDPR-aligned frameworks and ICCA-IBA practical guidance) increases the operational burden on parties and counsel, necessitating early-stage e-discovery and compliance planning to avoid evidentiary risk.
- Technological change — notably the adoption of AI for document review, predictive analytics, and translation — is reconfiguring cost structures and time-to-decision. Firms that incorporate validated AI tooling into repeatable workflows are able to compress timelines and reduce discrete review costs, but governance and admissibility considerations remain.
Strategic implications for 2026 corporate decision-makers
Based on the report’s modelling and practitioner interviews, we recommend a set of priority actions for boards and legal leaders entering 2026:
- Adopt a layered counsel strategy: maintain access to a small number of global lead firms for multi-jurisdictional steering, supplemented by specialized boutiques and forensic advisers for discrete phases and subject matter.
- Invest in pre-dispute readiness: allocate budget for contract remediation, arbitration clause hygiene, and standby expert arrangements to shorten mobilization time when disputes crystallize.
- Embed data protection and e-discovery protocols into commercial contracting and M&A diligence to reduce evidentiary surprises and preserve privilege across jurisdictions.
- Introduce a dispute-financing and cost governance framework that balances access to top-tier representation with alternative fee arrangements, capped budgets for phase work, and KPI-based vendor management.
- Pilot validated AI tools within a controlled governance framework to accelerate document triage, but retain human-in-the-loop controls for strategy-sensitive outputs and evidentiary validation.
- Update enforcement playbooks and asset-mapping processes to reflect evolving patterns of cross-border recoveries; coordinate closely with treasury and global tax teams to align recovery planning with balance-sheet considerations.
How to use this report in 90 days
For pragmatic adoption, the report includes a 90-day implementation roadmap that ties strategic choices to measurable milestones:
- Week 1–2: Rapid diagnostic using our dispute-exposure checklist and the counsel-selection scorecard to establish vendor shortlist.
- Week 3–6: Contract remediation sprints for high-risk contracts and deployment of e-discovery readiness measures at designated operational hubs.
- Week 7–12: Run a pilot integrating an AI-assisted review workflow on a live matter, coupled with a controlled costs baseline and defined escalation channels to board-level stakeholders.
Each milestone is accompanied by templated outputs (board memos, procurement RFx templates, and vendor governance SLAs) to accelerate adoption and reduce internal friction.
Trailer — what we intentionally withhold here
This article is designed to showcase the strategic shape and operational value of our market work while reserving the full, segment-level intelligence for subscribers. The complete report contains detailed regional and service-type breakdowns, granular provider benchmarking, and modelled scenario outputs (region-by-region and service-by-service) that corporate decision-makers use to finalize budgets and counsel panels. Those granular splits and comparator tables are intentionally omitted from this public summary to preserve the utility of the full dataset for purchasers.
Closing and next steps
2026 will be a year where preparedness, not hindsight, determines outcomes in international dispute resolution. PW Consulting’s Worldwide Dispute Advisory and International Arbitration Market report equips leaders with a translation layer from macro trend to executable playbook — combining market modelling, competitor intelligence, regulatory primers, and reproducible tools that shorten the path from insight to decision. For executive teams planning 2026 budgets, vendor panels, and dispute-readiness investments, the full report is an operationally material input to the planning cycle.
To access the full analysis, granular segmentation, and downloadable toolkits, please visit our report page and download the subscriber packet.
For detailed analysis of this topic, please visit the official page:Worldwide Dispute Advisory and International Arbitration Market
Lacy Lee
Senior Marketing Manager
[email protected]
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Romaian
 Portuguese (Brazil)
 Greek