
PW Consulting: Desktop Industrial Robot Market Poised to Grow at a 13.52% CAGR Through 2032
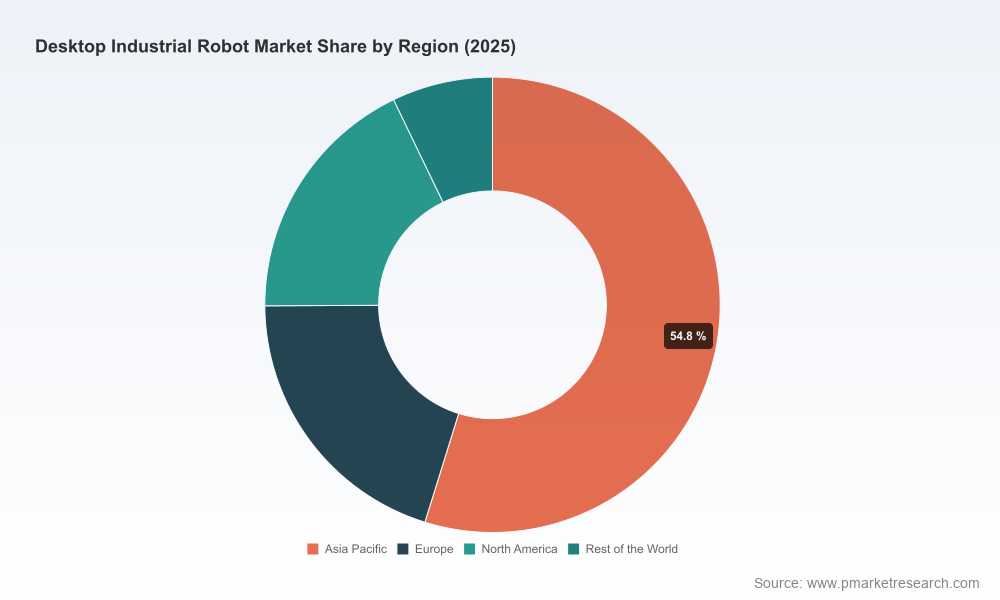
Desktop Industrial Robot Market — Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest market study, Desktop Industrial Robot Market (Base Year: 2025; Forecast Period: 2026–2032), equips executives with the commercial intelligence required to convert early investments in benchtop automation into durable operational advantage. Our analysis projects the desktop industrial robot market to grow from a 2025 baseline valuation of approximately USD 820 Million to near USD 2.0 Billion by 2032, at a compound annual growth rate (CAGR) of 13.52% across the forecast interval. This report blends quantitative forecasting with hands-on, executable guidance — the combination that senior leaders need to design 2026 budgets, capital plans, and partner ecosystems with confidence.
Worldwide Benchtop Hematology Analyzers Market
Why this report matters for 2026 strategy
- High-growth, capital-efficient automation. The projected 13.52% CAGR signals a sustained, above-market expansion window for compact automation solutions that reduce unit labor cost and improve throughput at low capital intensity.
- Decision-ready outputs. Beyond headline sizing, the report supplies deployment roadmaps, supplier scorecards, TCO models, and regulatory compliance checklists calibrated for the desktop form factor — all tailored for immediate adoption in 2026 planning cycles.
- Risk-adjusted scenarios. We model sensitivity to raw material volatility, standards evolution, and macro-driven demand shifts so procurement and strategy teams can stress-test vendor commitments and CAPEX timing.
Key market dynamics shaping 2026
Four interacting forces are redefining where and how desktop industrial robots create value:
Worldwide Nickel in the Automotive Market
- Industry 4.0 and high-mix, low-volume manufacturing. Smart-factory initiatives continue to prioritize flexible, modular equipment for rapid changeovers and lot-size-one production. Desktop robots — with their small footprint and rapid redeployability — are increasingly viewed as building blocks of micro-factories and localized production cells.
- Labor economics and adoption triggers. Rising wage pressure in electronics assembly and precision manufacturing has shortened payback periods for benchtop automation. Practical survey data in the report shows procurement thresholds and ROI targets that procurement and engineering teams use to greenlight pilots.
- Standards and safety governance. ISO 10218 and ISO/TS 15066 retain precedence for safety certification and risk assessment. Manufacturers seeking to integrate collaborative desktop arms into operator-adjacent workflows must align product selection and cell design to these standards to avoid integration delays and remediation costs.
- Supply-side constraints. Structural materials — primarily steel and precision aluminum alloys — remain the dominant components of desktop frames and arms. Supply-chain tightness and raw-material price fluctuations are factored into component lead-time modelling and inventory strategies in our forecast.
Where value will be captured (and where you should focus)
The report disaggregates the market along the traditional axes — product topology, application verticals, and geographic demand — and then overlays capability-led views (precision, cycle-time, safety features, and integration ease). We deliberately refrain from publishing the granular split in this summary; however, senior teams will find the following directional implications useful for 2026 prioritization:
Worldwide Standard Duplex Receptacle Testers Market
- Platform extensibility beats point-feature differentiation. Buyers increasingly favor arms and controllers that support modular end-effectors, software APIs, and plug-and-play vision rather than monolithic, feature-locked devices.
- Benchtop precision and miniaturized 6‑DoF capabilities open new use cases. Small-footprint articulated and SCARA alternatives compete on precision and repeatability in electronics, medical device assembly, and lab automation.
- Integration services determine margin capture. Vendors that combine hardware with certified integration partners and finance options capture larger TCV (total contract value) and accelerate enterprise adoption.
Competitive landscape: positioning and implications
The desktop industrial robot space combines established OEMs, specialized micro-robot manufacturers, and agile new entrants. Our market concentration analysis indicates a moderately concentrated market: the top three firms control roughly 42% of the market by revenue, while the top five account for about 58%. This structure creates room for both scale players and niche specialists to coexist — and for M&A or partnerships to materially shift competitive dynamics.
Representative strategic profiles (covered in the report) include:
- Janome (Japan): A heritage provider of Cartesian desktop systems focused on precision dispensing and screw-driving in small-footprint cells. Their strength lies in application-specific tooling and reliable hardware engineering.
- Dobot (Shenzhen): Aggressive product cadence in desktop collaborative platforms and multi-axis units, notably the MG400 family. Dobot’s rapid prototyping and channel presence make it an incumbent for light industrial use-cases and education-to-production pathways.
- DENSO Robotics / DENSO WAVE (Japan): Deep installed base in small assembly automation and SCARA technologies, with a reputation for durability in continuous manufacturing environments.
- Mecademic (Montreal): A leader in ultra-compact, high-precision 6-DoF robots, targeting benchtop metrology and micro-assembly — segments that prize repeatability over low cost.
- TOYO Robotics, TM Robotics, NITTOSEIKO, Elephant Robotics, USABotics and others: Each occupies differentiated roles — from distribution and systems integration to specialized product design for collaborative use-cases and domestic/regional demand.
Recent industry movements underscore strategic themes to monitor in 2026: accelerated product launches from collaborative arm manufacturers, trade-show-led technology diffusion (notably events that showcased desktop solutions in 2025), and an ongoing push for faster, higher-payload small-form-factor arms. These developments suggest a bifurcation: commoditization of basic pick-and-place capabilities and premiumization around precision, safety certification, and software integration.
Practical, actionable playbook for 2026
For executives looking to convert insight into outcomes, PW Consulting recommends the following six moves — all supported by templates, vendor scorecards, and TCO models included in the full report.
- Run targeted pilots tied to unit-economics milestones. Define clear KPIs (cycle-time, yield, operator-touch reduction) and set a strict decision gate (e.g., 6–9 month ROI horizon) to move from pilot to scale.
- Prioritize modular control architectures. Adopt controllers and middleware that enable third-party vision and end-effector attachments to futureproof automation cells against rapid capability shifts.
- Design for compliance and reduced integration latency. Embed ISO 10218/TS 15066 risk assessments and safety validation into procurement contracts to reduce retrofit costs and time-to-deployment.
- Secure dual-source supply strategies for critical structural components. Hedging supplier exposure for precision aluminum and key actuators reduces lead-time risk and supports accelerated rollouts.
- Leverage ecosystem partnerships for horizontal capabilities. Partner with local integrators and software houses to bundle installation, maintenance, and operator training into commercially attractive solutions.
- Use financing and subscription models to widen procurement aperture. Experiment with OPEX-based acquisition models for mid-market customers who face CAPEX constraints but need rapid automation uplift.
Report contents — what you receive
This study combines robust quantitative forecasting with operational playbooks and vendor intelligence. Key deliverables include:
- Bottom-up market sizing and scenario forecasts (2020–2032) with transparent methodology and sensitivity tables calibrated for commodity and demand shocks.
- Competitive benchmarking: in-depth profiles, product roadmaps, channel strategies, and partnership matrices for leading and emerging vendors.
- Go-to-market frameworks: account segmentation, pricing and lease models, integration partner selection criteria, and pilot-to-scale templates.
- Implementation resources: safety compliance checklists, TCO calculators in USD (report unit: Million), and case studies demonstrating realistic payback periods in electronics, medical, and precision engineering contexts.
- Strategic scenarios: three-year to seven-year stress tests that show how different input assumptions (material price shocks, regulatory tightening, or accelerated Industry 4.0 investment) affect adoption curves and vendor revenues.
How to use this intelligence in 2026
Use the report to prioritize portfolio investments, structure vendor contracts, and shape M&A or partnership programs that can accelerate market entry. Procurement teams will appreciate the supplier scorecards and validated TCO models; R&D and product teams will find the precision- and payload-focused roadmaps valuable for roadmapping; and senior leaders will receive scenario-based guidance to align capital allocation with strategic risk appetite.
Importantly, this release is a “trailer” rather than an exhaustive data dump. We deliberately withhold detailed subsegment tables and split metrics in this public summary to preserve the integrity of the report’s commercial dataset and to encourage direct access to the full analytical models and vendor dossiers.
Next steps
For access to the full report, granular subsegment tables, raw data files (CSV), and the vendor playbooks referenced here, please visit the PW Consulting report page. The full package includes the proprietary forecasting models and a one-hour briefing with our lead analysts to translate the insights into a tailored 2026 action plan for your organization.
For detailed analysis of this topic, please visit the official page:Desktop Industrial Robot Market
Lacy Lee
Senior Marketing Manager
[email protected]
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)